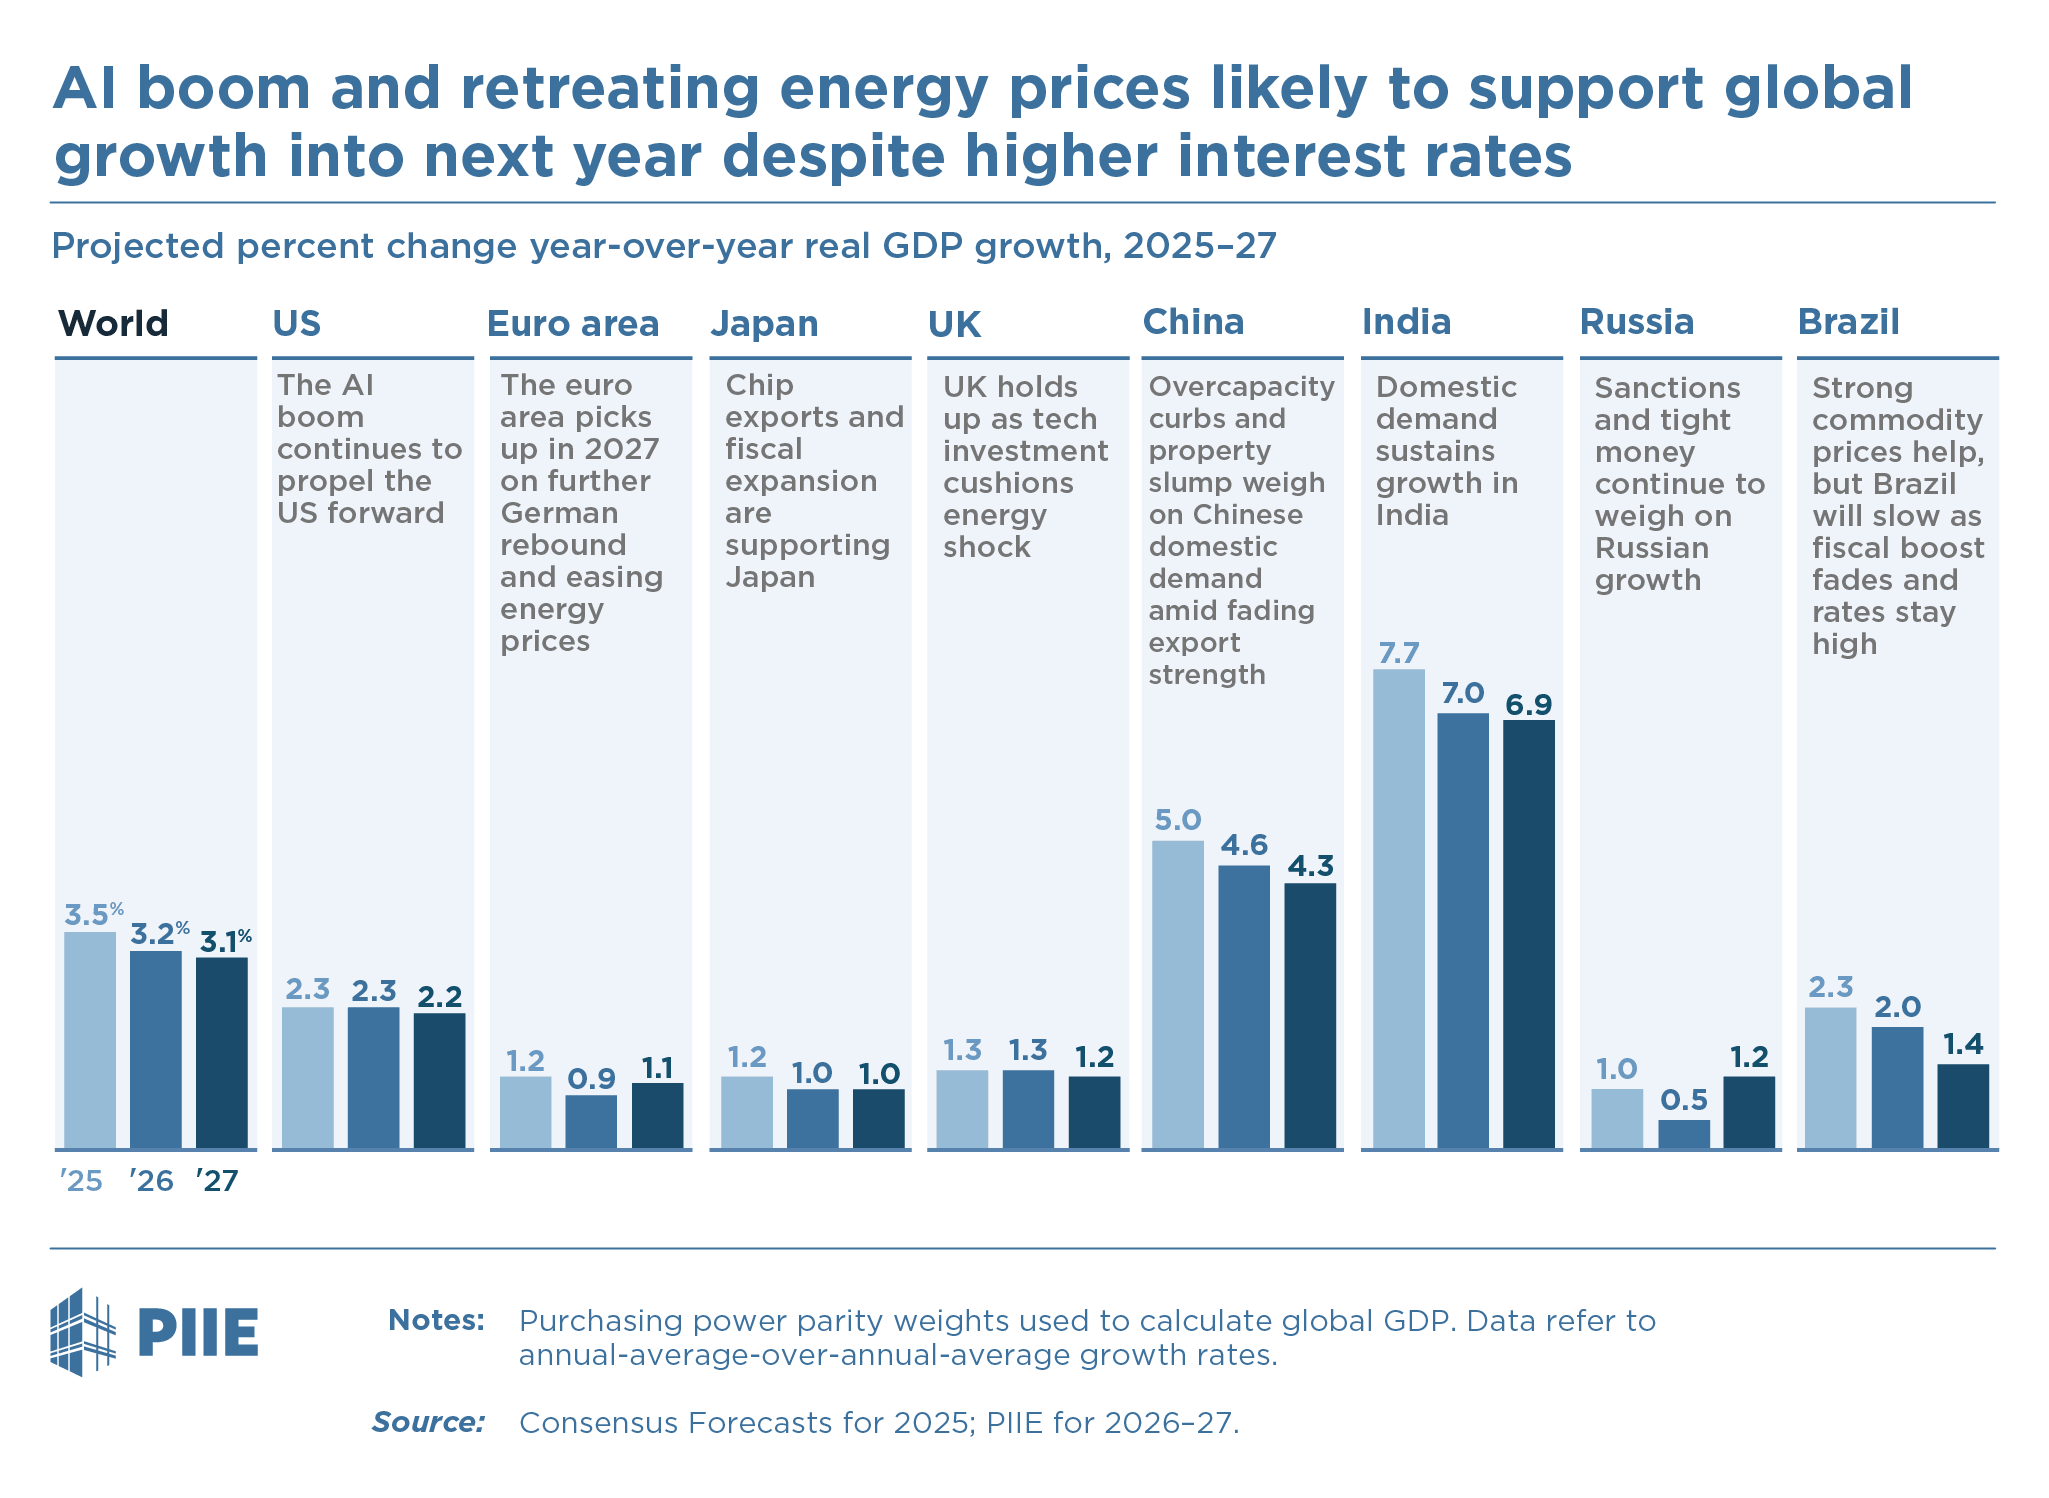
The global economy continues to expand at a solid pace, as the artificial intelligence (AI) boom helps cushion the effects of increased energy prices, inflation, and interest rates. Real global GDP is projected to rise 3.2 percent in 2026 and 3.1 percent in 2027, according to analysis presented at the Peterson Institute for International Economics Fall 2026 Global Economic Prospects event. Higher interest rates will be an important force holding back economic growth next year, with the drag tempered by a gradual retreat in energy prices. US economic growth remains healthy, powered by robust consumer spending and business investment. Real US GDP is projected to rise 2.3 percent this year and 2.2 percent next year.
Higher energy prices are weighing on growth and pushing up inflation
The war in Iran delivered a significant adverse shock to energy markets early this year. Brent crude oil prices are now around $100 per barrel, close to 40 percent above their level at the beginning of the war. Prices for European natural gas, diesel, and some other refined products have risen by much more. The forecast assumes that energy prices will gradually retreat in line with futures markets. For example, Brent is expected to fall to just over $80 per barrel by the end of 2027, within $10 of its pre-war level.
The rise in energy prices has spurred higher inflation in most countries. Although inflation remains much lower than its highs of the early 2020s, the recent rise has been large enough to be of material concern to many households, businesses, and central banks.
Against this backdrop, interest rates are on the rise. The US Federal Reserve and other central banks have started to raise policy rates, and more increases are likely in coming months. Meanwhile, government borrowing rates have increased sharply. In many advanced economies, these rates have reached their highest level since the global financial crisis. The higher rates reflect not only the expectation of higher policy rates but also greater concerns about fiscal sustainability as well as fierce global competition for loanable funds related to the AI buildout.
Growth in most of the major economies next year is likely to be similar to this year's pace
The energy shock and higher interest rates are important common factors shaping the global economic outlook. The AI boom is expected to continue supporting growth in a number of economies through its effects on investment and stock prices, with an especially pronounced boost to growth in the United States. Among the other major advanced economies, growth in the euro area is expected to pick up modestly in 2027, with a further rebound in Germany. Japan is likely to continue its above-trend growth, supported by strong microchip exports and fiscal expansion. Economic momentum in the United Kingdom is also holding up, as technology investment cushions the energy shock.
The outlook for emerging-market economies is more varied. India continues to lead among the major emerging economies, with strong domestic demand sustaining growth. In contrast, Chinese domestic demand remains weak given overcapacity and an ongoing drag from the property slump, and the strength of Chinese exports is likely to fade next year. Russia's economy remains constrained by sanctions and tight monetary policy. Brazil has benefited from strong commodity prices, but growth is likely to slow as this year's fiscal boost fades and interest rates remain high.
Strong demand is supporting growth in the United States, while inflation remains elevated
In the United States, private demand remains robust. As a result, the US labor market continues to be healthy, with the unemployment rate close to the level the Fed considers consistent with full employment. However, the strong economy, together with the increase in energy prices since the beginning of the war with Iran, have led to a significant pickup in inflation.
US consumer spending has risen much more briskly this year than last year, even as consumer sentiment has declined and disposable income growth has risen only a bit. Continued sizable gains in household wealth, fueled by AI optimism in the stock market, appear to be the main factor underpinning the spending pickup. The important role of this driver points to a risk to the forecast: If equity prices were to undergo a significant correction, household spending could weaken sharply.
US business investment has surged this year and is likely to remain strong, driven by AI-related spending on equipment. This spending should boost US output growth over the longer run. Its immediate contribution to US GDP is more limited, however, because much of the equipment is imported.
The Fed is carefully monitoring the effects of the energy price shock on inflation. At its September meeting, the rate-setting Federal Open Market Committee (FOMC) raised the policy rate by 0.25 percentage point. Additional hikes will likely be needed to cool the economy and maintain the Fed's inflation-fighting credibility. The FOMC will be data dependent, but the most likely outcome is three more quarter-point rate increases, in December, January, and March. Inflation expectations have remained broadly stable this year, although they remain above pre-COVID-19 norms.
Against this backdrop, US inflation is expected to retreat over the coming year as energy prices gradually decline and tighter monetary policy restrains demand. Core inflation is likely to fall more gradually than headline inflation, given the general persistence of nonhousing services inflation as well as upward pressure from lagged diesel cost pass-through and chip shortages. All told, the personal consumption expenditures (PCE) price index is projected to rise 3.7 percent over the four quarters of 2026, and core PCE prices are projected to rise 3.3 percent. PCE inflation is projected to moderate to 2.3 percent in 2027, while core PCE inflation eases to 2.7 percent.
US fiscal risks are rising, though a crisis is not imminent
The US outlook will also be shaped by high and rising federal debt and deficits. Net federal interest payments relative to GDP have already surged to their highest level since the 1990s and, under current policies, the Congressional Budget Office (CBO) projects them to rise much further. With the level of federal debt so high, net interest payments are especially sensitive to interest rates. The 10-year Treasury yield is already about a percentage point above what the CBO projected for this year when it published its latest projection in early 2026. A higher-than-projected path of interest rates on government borrowing would intensify the snowballing of federal debt, with higher interest payments pushing up debt and, in turn, generating still higher interest payments.
A further concern about the US fiscal outlook is that ownership of Treasury securities has shifted toward more leveraged and price-sensitive investors. Foreign official holdings have declined, while holdings by households and hedge funds have increased. Because hedge funds use leverage to hold Treasury securities, a shock that raises interest rates and generates losses could be amplified by their need to deleverage.
AI will probably improve the fiscal outlook, but it will not solve the problem. Faster productivity growth reduces deficits, but it also generally leads to higher interest rates, which can increase deficits. If income shifts toward capital owners, the lower average tax rate on capital could raise deficits, while job losses and higher inequality could spur more federal spending and programs.
That said, a US fiscal crisis does not appear imminent. Interest rates remain below their levels in the 1980s and most of the 1990s, and the US economy remains on a solid footing. Still, as in many countries, the long-run US fiscal outlook is unsustainable, and the risk of a crisis has grown. Rising interest payments relative to GDP may eventually build public pressure for action in the United States, but political polarization argues against meaningful policy action in the near term.
Data Disclosure
This publication does not include a replication package.